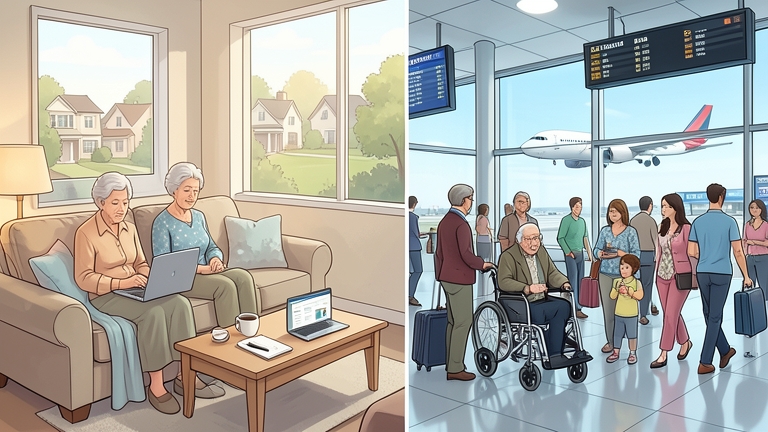
Whether you are planning a cross-country road trip to see family or an overseas getaway, packing your bags is only half the prep. Health care coverage does not always travel as smoothly as you do. While standard Medicare steps up for emergency care within the United States, international travel rules and out-of-state network restrictions can catch even seasoned travelers off guard. This article presents a Medicare Travel Readiness Quiz to help you test your knowledge, spot hidden coverage gaps, and make sure you are protected wherever your itinerary takes you. And do not worry if you miss an answer; you can follow the links below the quiz to brush up on your knowledge.
Understanding Medicare Coverage at Home
Medicare provides robust coverage for emergency and urgent care when you are traveling within the United States and its territories. Original Medicare Part A covers hospital stays, while Part B covers doctor visits and outpatient services. However, many beneficiaries assume that all services are covered anywhere in the country. In reality, Medicare generally covers emergency care at any hospital that accepts Medicare, but routine or non-emergency care may require you to see providers enrolled in the program. If you have a Medicare Advantage plan, your coverage may be restricted to a network, making out-of-state travel more complicated. Before you head out, verify whether your plan includes emergency coverage nationwide and whether prior authorization is needed for certain services.
Out-of-State Network Restrictions
Medicare Advantage plans often operate within specific service areas. If you travel outside that area for non-emergency care, you could face higher out-of-pocket costs or no coverage at all. Some plans offer a travel benefit that extends emergency coverage, but routine visits may not be included. Always check with your plan provider before traveling. For Original Medicare, there are no network restrictions, but you must ensure the provider accepts Medicare assignment. This is usually not an issue for emergency care, but for planned medical services, confirmation is essential.
Medicare Coverage Abroad
One of the most common misconceptions is that Medicare covers health care expenses outside the United States. In nearly all cases, Original Medicare does not pay for medical care received in a foreign country, including Canada, Mexico, Europe, Asia, or anywhere else. There are very limited exceptions, such as when you are in the United States but near the border and a foreign hospital is closer, or on a cruise ship within territorial waters. These exceptions are rare and do not provide comprehensive coverage. Therefore, relying solely on Medicare for international travel is a risky proposition.
The 6-Hour Rule for Cruises
If you are planning a cruise, Medicare may cover emergency services if the ship is within U.S. territorial waters, typically defined as within six hours of a U.S. port. This is known as the 6-Hour Rule. Once the ship ventures beyond that limit, Medicare coverage generally ends. For comprehensive protection on a cruise, you should consider travel insurance or a Medigap plan that offers foreign travel emergency coverage.
The Medicare Travel Readiness Quiz
Take this quick quiz to assess your travel readiness. Answer each question honestly, and then review the explanations to fill any gaps in your knowledge.
Question 1
You are on vacation in Florida and need emergency care. You have Original Medicare. Will your hospital stay be covered?
Answer: Yes. Original Medicare covers emergency care at any hospital in the United States that accepts Medicare, regardless of which state you live in.
Question 2
You are visiting Paris and require urgent medical attention. Does Original Medicare cover this expense?
Answer: No. Original Medicare does not cover health care services outside the United States except in very rare circumstances.
Question 3
You have a Medicare Advantage plan with a network limited to your home state. You need a routine checkup while visiting your daughter in another state. Will your plan cover this visit?
Answer: Probably not. Most Medicare Advantage plans do not cover routine or non-emergency care outside their service area. Emergency care may be covered, but routine visits usually are not.
Question 4
You are on a cruise ship 10 hours from the nearest U.S. port. You suffer a heart attack and are treated on the ship. Is this covered by Original Medicare?
Answer: Possibly not. Under the 6-Hour Rule, coverage applies only if the ship is within six hours of a U.S. port. Beyond that, Medicare typically does not cover the care.
Question 5
You are considering buying a Medigap policy. Which Medigap plans offer foreign travel emergency coverage?
Answer: Medigap Plans C, D, F, G, M, and N offer foreign travel emergency coverage, but only for the first 60 days of your trip and with a lifetime limit. You pay a deductible, and the plan covers 80% of eligible emergency care abroad.
How to Protect Yourself When Traveling
Knowing the gaps in Medicare coverage is the first step. The second step is taking action to close those gaps. Here are practical strategies to ensure you are protected both at home and abroad.
Consider a Medigap Policy
Medigap, or Medicare Supplement Insurance, can fill many of the gaps left by Original Medicare, including certain foreign travel emergencies. Plans C, D, F, G, M, and N include coverage for emergency care outside the United States. This benefit covers up to 80% of medically necessary emergency care after a $250 deductible, with a lifetime limit of $50,000. However, it is only valid during the first 60 days of your trip. If you travel frequently or for extended periods, this may not be sufficient, and you should consider additional travel health insurance.
Purchase Travel Health Insurance
For international trips, a standalone travel health insurance policy is highly recommended. These policies can cover emergency medical evacuation, hospitalization, doctor visits, and repatriation. Many policies also cover trip cancellation and interruption. When shopping for a policy, look for one that specifically mentions coverage for pre-existing conditions if needed, and ensure the coverage limits are adequate for the destination. For example, medical evacuation from a remote location can cost tens of thousands of dollars.
Check Your Medicare Advantage Plan Benefits
Some Medicare Advantage plans offer a travel benefit that extends emergency coverage outside the service area. This benefit varies widely by plan and insurer. Call your plan provider and ask specific questions: What is covered outside my service area? Is there a copay for emergency room visits in another state? Is urgent care covered? Do I need prior authorization? Write down the answers and keep them with your travel documents.
Use the 6-Hour Rule to Your Advantage
If you are planning a cruise, choose itineraries that keep the ship within six hours of a U.S. port for as long as possible. This maximizes the chance that Medicare will cover any emergency that arises. However, do not rely solely on this rule. Supplemental coverage is still the safest option.
The 12 Travel Tips Every Retiree Needs to Know
Beyond insurance, there are logistical steps retirees should take before any trip. These tips help ensure a smooth journey and quick access to care if needed.
Tip 1: Carry Your Medicare Card
Always travel with your red, white, and blue Medicare card, as well as any supplemental insurance cards. Keep a digital copy in your phone and a physical copy in your bag.
Tip 2: Know the Local Emergency Number
In the United States, dial 911. In many other countries, the number is different. For example, in the European Union, dial 112. Save the local emergency number in your phone before you travel.
Tip 3: Research Hospitals in Advance
Before you leave, identify hospitals and urgent care centers near your destination that accept Medicare. For international trips, research facilities with English-speaking staff and good reputations.
Tip 4: Bring a Copy of Your Medical History
Carry a brief summary of your medical history, including allergies, medications, chronic conditions, and emergency contacts. This can be lifesaving if you are unable to communicate.
Tip 5: Pack Enough Medication
Bring more than enough prescription medication for your trip, plus a few extra days in case of delays. Keep medications in their original bottles with labels, and carry a copy of your prescriptions.
Tip 6: Check for Vaccine Requirements
Some countries require specific vaccinations for entry. Check the Centers for Disease Control and Prevention website for destination-specific recommendations and get any needed shots at least four weeks before departure.
Tip 7: Understand Your Plan’s Prior Authorization Rules
If you have a Medicare Advantage plan, some services may require prior authorization even in an emergency. Know these rules before you need care.
Tip 8: Consider Medical Evacuation Insurance
Medical evacuation insurance is a separate product that covers the cost of transporting you to a hospital of your choice or back to the United States if needed. This is especially important for remote destinations.
Tip 9: Notify Your Plan of Extended Travel
If you plan to be away for more than 30 days, some Medicare Advantage plans may have specific rules. Notifying them in advance can prevent coverage disputes.
Tip 10: Keep Contact Information Handy
Store the customer service numbers for Medicare, your Medigap plan, and your travel insurance provider in your phone and on paper.
Tip 11: Use Telehealth Services
Many Medicare Advantage plans offer telehealth options that can connect you with a doctor from anywhere. This can be a good first step if you have a minor issue while traveling.
Tip 12: Review Your Coverage Annually
Your health needs and travel plans change. Each year during Open Enrollment, review your Medicare and supplemental coverage to ensure it still meets your needs.
The 10 Most Valuable Vacation Destinations for Retirees in 2026
For those ready to plan their next adventure, certain destinations offer excellent value, accessibility, and health care infrastructure for retirees. Destinations like Portugal, Costa Rica, and Spain are popular for their affordable health care systems and welcoming environments. Before booking, check whether your Medigap plan’s foreign travel emergency coverage or your travel insurance policy includes these countries. Always verify that the local health care system meets your needs, especially if you have chronic conditions requiring regular monitoring.
The 10 Best Splurge Destinations for Retirees in 2026
If you prefer luxury travel, destinations such as Japan, Switzerland, and the Maldives offer world-class experiences but also come with higher health care costs. In these locations, comprehensive travel insurance with high coverage limits and medical evacuation is non-negotiable. Ensure your policy covers the full duration of your stay and includes repatriation. Even if you have Medigap coverage, it may not be sufficient for expensive medical care in these regions.
Ultimately, Medicare travel readiness comes down to knowledge and preparation. By understanding what your policy covers at home and abroad, taking the Medicare Travel Readiness Quiz seriously, and investing in supplemental coverage where needed, you can travel with confidence. Whether you are visiting family in another state or exploring a new continent, your health coverage should be as prepared for the journey as you are. Do not leave your well-being to chance. Review your plan, learn the rules, and close every coverage gap before you depart.